Your First Home is a new government scheme announced on 26 September 2026. It is expected to let eligible first-time buyers in England buy a new build home with a 2.5% deposit, supported by a 20% government-backed equity loan with an initial interest-free period. The full rules, including eligibility, income and price caps and launch dates, will be confirmed at the Budget on 28 October 2026.
What is the Your First Home scheme?
Your First Home is a government-backed equity loan scheme for first-time buyers in England. It is designed to help people who can afford monthly mortgage payments but struggle to save a large deposit, particularly those without help from family.
Many people are already calling it the new Help to Buy scheme. The previous Help to Buy equity loan closed in 2023 and needed a 5% deposit. Your First Home is expected to work in a similar way, but with the deposit halved to 2.5%.
It is also separate from the First Homes scheme, which offers discounted homes to eligible local buyers.
How would a 2.5% deposit work?
Under the announced proposals, your purchase would be made up of three parts:
- a 2.5% deposit from you
- a 20% equity loan from the Government
- a mortgage for the remaining 77.5%
Because you would need to borrow less from a mortgage lender than with a standard 95% mortgage, your monthly repayments could be lower. The Government says buyers using the scheme could save hundreds of pounds per month compared with a 95% mortgage.
What is a 20% equity loan?
An equity loan is a loan from the Government towards the cost of your home, secured against the property. For Your First Home, it is expected to cover 20% of the purchase price, with no interest to pay for an initial period.
The loan is repaid later, usually when you sell or remortgage. Under the previous Help to Buy scheme, the amount repaid was linked to the home’s value at that time, and interest was charged after the interest-free period ended. The exact repayment terms for Your First Home have not been published yet, so it is worth checking the details carefully once they are confirmed.
Who could be eligible?
Based on the announcement so far, the scheme is expected to be open to:
- first-time buyers in England
- buying a new build home
- from a developer that has signed up to the scheme
The Government has also said there will be a household income cap and local property price caps. The exact limits will be set out at the Budget.
Will the scheme only apply to new build homes?
Yes. As announced, Your First Home is specifically for new build homes bought from developers taking part in the scheme. It will not apply to resale homes.
When will Your First Home launch?
Full details, including costs and timings, will be announced at the Budget on 28 October 2026. The Government has said pre-registration is expected to open by the end of 2026. Dates for when buyers can complete a purchase using the scheme have not yet been confirmed.
Is Broadgate Homes taking part in Your First Home?
We’re actively looking into it. Our team is already reviewing how Your First Home could work across our developments, because we’d like to be able to offer this opportunity to first-time buyers at The Furlongs at Holland Park in Spalding and Gleneagles Drive in Woodhall Spa.
Developers will need to sign up to the scheme, and registration isn’t open yet. Once the full details are confirmed at the Budget on 28 October, we’ll confirm our plans and share them here. If you’d like to be among the first to hear, register your interest with our sales team.
It feels proactive without committing Broadgate to anything Carolyne and the finance team haven’t agreed.
What could Your First Home look like on a Broadgate home?
To make the numbers real, here are two illustrative examples based on current starting prices at our developments.*
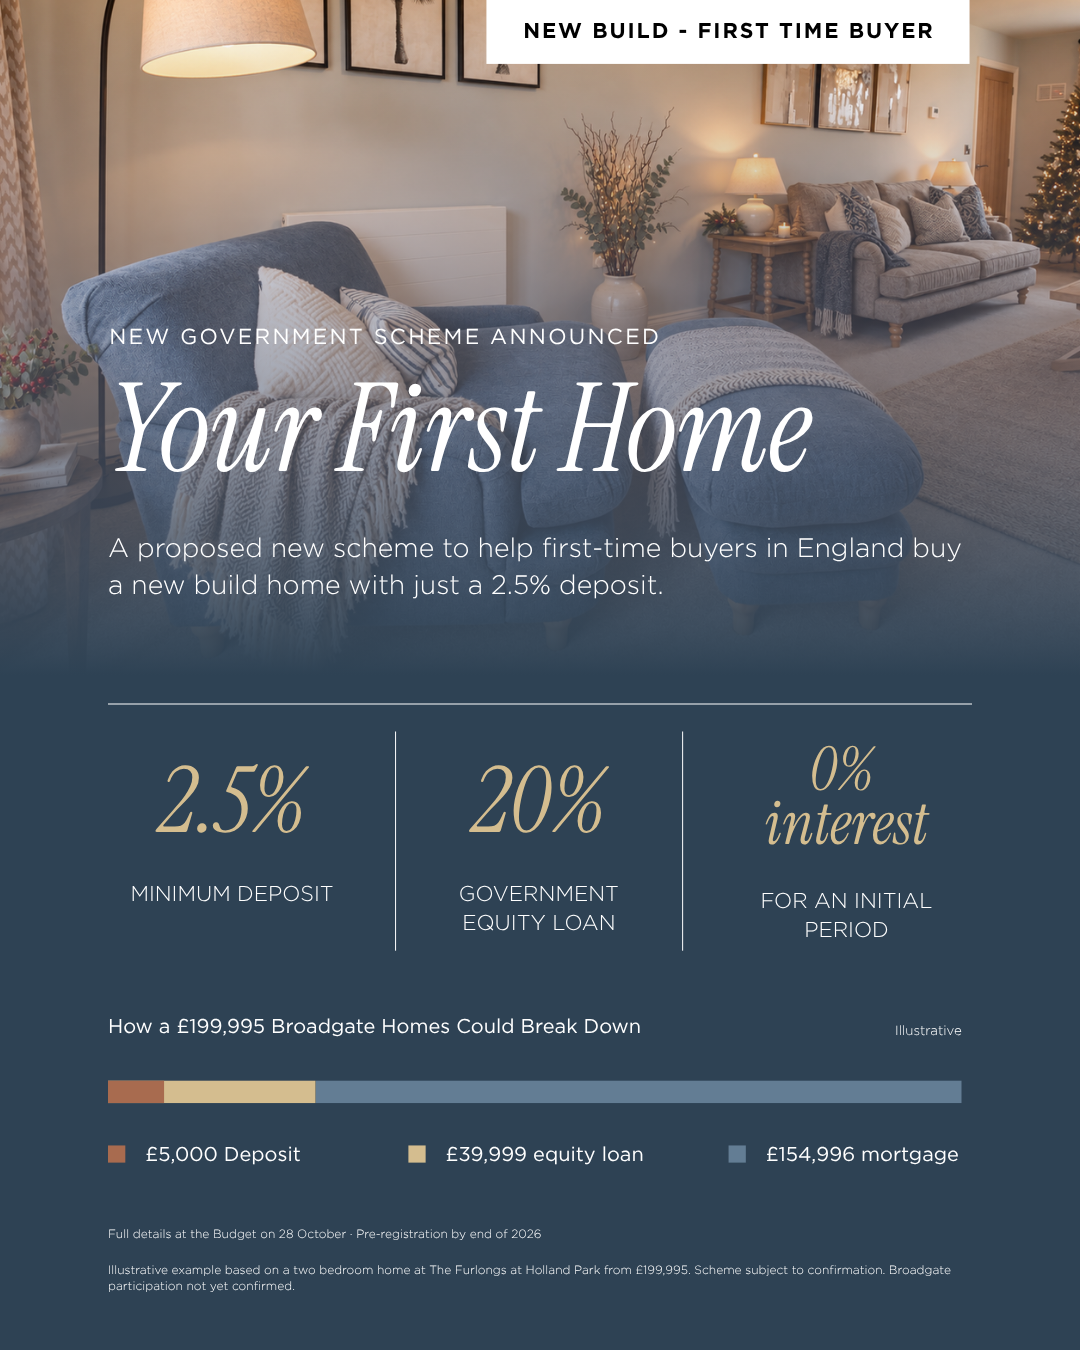
The Furlongs at Holland Park, Spalding: two bedroom home from £199,995
| Typical 95% mortgage | Your First Home (illustrative) | |
|---|---|---|
| Your deposit | Around £10,000 (5%) | Around £5,000 (2.5%) |
| Government equity loan | None | Around £39,999 (20%) |
| Mortgage needed | Around £189,995 (95%) | Around £154,996 (77.5%) |
Gleneagles Drive, Woodhall Spa: homes from £267,995
| Typical 95% mortgage | Your First Home (illustrative) | |
|---|---|---|
| Your deposit | Around £13,400 (5%) | Around £6,700 (2.5%) |
| Government equity loan | None | Around £53,599 (20%) |
| Mortgage needed | Around £254,595 (95%) | Around £207,696 (77.5%) |
In both examples, the deposit you would need to save is halved. The mortgage is also around £35,000 smaller at The Furlongs and around £47,000 smaller at Gleneagles Drive. That’s why the scheme could make a real difference to first-time buyers who are ready for homeownership but still saving towards a deposit.
Should I wait for Your First Home or buy now?
It depends on your circumstances. The scheme could be a great option once it launches, but eligibility, price caps and timings are not yet known.
If you are ready to move now, or hoping to be settled before Christmas, there is support available today. At The Furlongs and Gleneagles Drive, buyers can currently choose a 5% deposit contribution or stamp duty paid, plus legal fees up to £2,000 covered.** Our sales team can talk you through what that could mean for you.
What can first-time buyers do now?
- Keep saving: a 2.5% deposit would be around £5,000 on a £199,995 home, or around £6,700 on a £267,995 home.
- Speak to an independent mortgage adviser about what you could borrow.
- Get a mortgage agreement in principle so you are ready to move quickly.
- Visit our show homes to see which homes suit you.
- Register your interest with our team to hear as soon as we know more after the Budget.
Find out more
To talk through your options or book a viewing, call 01406 380 532 or visit broadgate-homes.com.
*Illustrative example only, based on the Government’s announcement of 26 September 2026. Your First Home is not yet available, and full eligibility criteria, price caps and terms will be confirmed at the Budget. Broadgate Homes is currently reviewing the scheme and participation is not yet confirmed. Figures are rounded and are not a mortgage offer or financial advice. Please speak to an independent mortgage adviser. Your home may be repossessed if you do not keep up repayments on your mortgage.
**T&Cs apply. Choose either a 5% deposit contribution or stamp duty paid, plus legal fees up to £2,000. Available on selected plots. Excludes non-UK residents and buyers with additional properties. Speak to our sales team for full details.